

The primary market reopens this week with two mainboard issues: Crystal Crop Protection’s ₹455 crore IPO and Coal India’s ₹8,981 crore sale of part of Mahanadi Coalfields. The minimum investment for each is the same ₹14,960, but the two businesses offer very different risks.
The IPO market has been quiet for most of November. The last mainboard IPO, Bombay Coated & Special Steels, closed for bidding on 2 November. Since then, the secondary market has risen more than 11% while the primary market has had no new mainboard issues.
That changes this week. Crystal Crop Protection opens today, Mahanadi Coalfields opens on Thursday, and an SME issue, Watrana Rentals, also opens on Thursday. Both mainboard issues require a minimum investment of exactly ₹14,960, but they are very different offerings.
Crystal Crop Protection: a growing agrochem business with debt to cut
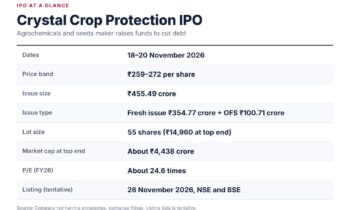
Crystal Crop, founded in 1994, sells fungicides, insecticides and herbicides, as well as bio-stimulants and vegetable, field and flower seeds.
Its acquired brands include Bavistin, Tilt, Proclaim and Blue Copper.
Revenue grew from ₹2,229.93 crore in FY24 to ₹3,151.97 crore in FY26. Net profit rose from ₹87.24 crore to ₹144.91 crore over the same period, and the EBITDA margin widened from 9.4% to 14.5%.
Debt is the main issue. Borrowings were ₹952 crore at the end of June, and finance costs rose to ₹89.16 crore in FY26. About ₹270 crore of the IPO proceeds will repay debt, which should lift future profits.
The company’s return on net worth of about 7.1% is below that of most listed peers, so the 24.6 times P/E is above the peer average of about 20 times. Investors are paying for continued margin improvement.
For an independent analyst’s take on the issue, read IPO analyst Dilip Davda’s review of the Crystal Crop Protection IPO here.
Mahanadi Coalfields: a large, slow-growing business
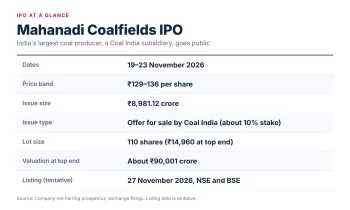
Mahanadi Coalfields (MCL) is India’s largest coal producer by output. It mainly mines non-coking coal for power plants, operates 17 mines in Odisha and has more than 20,500 permanent employees.
Coal India is selling about 10% of the company, so MCL itself will receive no money from the issue, and Coal India’s stake will fall to about 90%.
The valuation is low. MCL reported net profit of ₹4,879 crore in the first half of FY27. Doubling that gives an annualised profit of nearly ₹9,760 crore, so the top of the price band values it at roughly 9 times annualised earnings (our calculation). Profit growth is slow, though: first-half profit rose only 6.7%.
The prospectus lists several risks. The top 10 customers provided about 56% of FY26 revenue. MCL has large receivables from Andhra Pradesh power utilities, about ₹1,930 crore and ₹502 crore.
It faces demand notices of about ₹2,864 crore for production above environmental clearance limits, which it is contesting. It also flags a possible mineral levy liability that Coal India’s legal team has estimated at ₹31,227.80 crore.
MCL says it has received no quantified demand and does not treat this as an established liability. That estimate is about a third of MCL’s IPO valuation, so investors should read that section of the prospectus carefully.
Recent Coal India listings have performed differently. Bharat Coking Coal, which listed in January, is about 29% below its debut price. CMPDI, which listed in March, is up more than 18%.
Grey market premiums for both are on, however, a little lukewarm on trades. Crystal Crop is quoting at about ₹19, Mahanadi’s GMP has nearly halved in three days to about ₹3. Note GMP changes quickly and is no indicator of listing price or demand.
About The Author