

Alembic Pharma’s shares jumped 20% after an 81% rise in profit, on the same day Zydus and Biocon reported sharp declines. The difference comes down to where each company’s growth comes from.
Indian pharma results on Wednesday showed how differently drugmakers are performing this season.
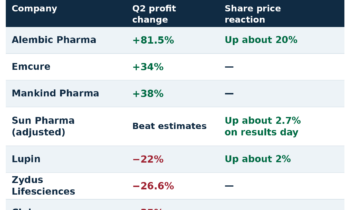
Alembic Pharmaceuticals reported consolidated net profit of ₹335.17 crore, up 81.5% from ₹184.71 crore a year earlier. Revenue rose 36.3% to ₹2,603 crore, and margins improved. The shares rose about 20%, trading near ₹912.65 in the afternoon.
Zydus Lifesciences reported consolidated net profit of ₹926 crore, down 26.6% from ₹1,261 crore, even as revenue grew 29%.
Biocon reported net profit attributable to shareholders of ₹41.3 crore, down 51% from ₹84.5 crore.
The paths diverge
The split follows the pattern seen across Indian pharma this season.
Companies whose profits depended heavily on a few high-margin US generic drugs are reporting lower profits as competition enters those markets and prices fall. Lupin, Cipla and now Zydus have reported falling profits despite revenue growth. That combination of higher sales and lower profit is the clearest sign that margins are falling. Zydus’s revenue grew 29% while its profit fell 27%, which means its costs or product mix have moved sharply against it.
Biocon’s position is different. It has invested heavily in biosimilars, complex copies of biological drugs, which require large spending on research, manufacturing and regulatory approvals before they produce returns. Its profit is small compared with its revenue and has been volatile as it carries that investment.
Alembic stands apart because it is growing revenue and margins at the same time. Its 36% revenue growth and 81% profit growth suggest it is benefiting from new US launches while running its business more efficiently, a combination that is now rare in the sector.
The markets reaction
A 20% one-day rise is unusual for a mid-sized pharma company, and it reflects how far the results exceeded expectations.
Alembic is smaller than Sun Pharma, Lupin or Zydus. When a smaller company reports results far above expectations, the price adjustment is often sharp, because fewer analysts cover it and its share price had not built in such strong growth. A near doubling of profit also changes its valuation significantly: a company that looked fully priced on old earnings can look inexpensive on new ones.
Lupin’s reaction the same morning makes a useful comparison. Lupin’s shares rose about 2% despite a 22% profit fall, because the market had already priced in weak results. Alembic’s rose 20% because the market had not priced in strong ones. In both cases, the share price moved on the gap between results and expectations, not on the results alone.
For investors, the sector can no longer be treated as a single trade. A few years ago, Indian pharma stocks moved largely together, driven by the US generics cycle. Now the gaps between companies are wide: from Alembic’s 81% profit growth to Biocon’s 51% decline in the same week.
Drugmakers with a steady flow of new, harder-to-copy launches and a strong domestic base are performing best. Those that relied on a small number of US blockbusters are seeing profits fall as competition arrives.
About The Author